Is the financial advice you were given actually good for you?
Upload your plan, proposal or record of advice. Our AI checks it against South African rules and live fund data, screens for scams and unlicensed advisers, and gives you a plain-language list of red flags to take back to your adviser.
We review advice — we never sell or recommend products.
Your review
5.8
/ 10 overall
Platform, fund and adviser fees stack up to a high total annual cost
Tax-free savings allowance left unused this year
Adviser and product provider found on the FSCA register
Checked against SA rules & benchmarks
FSCA licence & scam screening
Never recommends products
Your reviews are visible only to you
A second opinion in three steps
No jargon, no sales pitch — just a clear read on the advice you've already been given.
Upload your documents
Tell us what you're trying to achieve, then upload your plan, proposal, fund fact sheets or record of advice — PDF, Word or a photo of a printed page.
AI agents check it
Agents extract the facts, pull live fund and cost data, check the adviser and product are properly licensed, and screen for scam red flags. A reviewer model trained on SA advice then tests the plan against SA rules and benchmarks.
Get a plain-language report
A score out of 10, the red flags in order of seriousness, simple diagrams, and a specific list of questions to take back to your adviser.
Is your adviser licensed? Is the investment real?
The most damaging advice isn't a high fee — it's money handed to an unlicensed adviser or a scheme that was never regulated. Every review runs these checks before the plan itself is assessed.
Licence & legitimacy check
We research the adviser, their firm, the product and the product provider.
Whether each appears on the FSCA register
Whether the adviser has been debarred
Publicly reported complaints and warnings — and strong ratings and good standing
If registration can't be confirmed, the report says so plainly rather than guessing
Scam & Ponzi screen
We look for the classic warning signs of an investment that isn't what it seems.
Guaranteed or "risk-free" returns, or returns that look too good to be true
Pressure to act fast
Opaque or offshore structures, or promoters with no verifiable FSCA registration
Anything suspicious gets a clear, sourced warning at the top of your report
Eight categories, checked against real SA rules
The same areas a qualified planner would look at. Every flag shows the evidence from your plan, why it matters, and the SA rule or benchmark behind it.
Costs
High or layered fees that quietly eat into your returns.
Product suitability
A product that doesn't fit your goal or how long you'll invest.
Asset allocation
An investment mix out of step with your risk profile and timeline.
Tax efficiency
Tax breaks left on the table, like TFSA and retirement annuity allowances.
Retirement
Too little saved, the wrong annuity, or an income that may not last.
Risk / Insurance
Too much cover, too little, or the wrong type for what you need.
Estate planning
Costs and cash shortfalls your family could face when settling your estate.
Behavioural / Process
Needless switching, chasing performance, conflicts of interest, or no needs analysis.
Good advice is worth protecting
Financial planning is as much art as science — the right plan depends on someone's goals, temperament and circumstances, and reasonable advisers can disagree. That's exactly why judging good advice in the abstract is hard. But a genuinely skilled, engaged adviser has a measurable, well-documented impact on outcomes:
~8.5%
gap between what investors earned and what the market returned in 2024
The average equity fund investor earned 16.5% while the S&P 500 returned 25.1% — an ~848 basis-point shortfall driven almost entirely by bad timing: chasing returns, panic-selling, and switching at the wrong moment.
20 years
of sustained underperformance by the average investor
Over 2004–2024 the average equity fund investor returned 9.24% p.a. versus 10.35% p.a. for the S&P 500 — a gap that compounds into a dramatically smaller retirement pot over a working lifetime.
~3% a year
net value good advice can add, on Vanguard's estimate
Vanguard's "Advisor's Alpha" research attributes roughly half of that to behavioural coaching alone — an adviser talking a client out of the exact panic-selling and performance-chasing mistakes DALBAR measures above.
Sources: DALBAR Quantitative Analysis of Investor Behavior (QAIB) and Vanguard, "Advisor's Alpha". Figures are from long-running US studies — the most rigorously measured data available — cited here as illustrative evidence that engaged, competent advice has a real, quantifiable value; the same behavioural patterns show up in every market, including South Africa's.
Judging “good” advice is hard. Spotting bad advice isn’t.
We're not in the business of telling you what the perfect plan looks like — that depends on factors no algorithm can fully weigh. But decades of financial-planning theory, SA regulation and plain benchmark maths make the bad patterns easy to name: excessive layered costs, a product that doesn't match the goal, an asset mix out of step with risk profile and horizon, an unused tax allowance, an unsuitable annuity, over- or under-insurance, an estate that can't be settled without a fire sale, or switching that benefits the adviser more than the client.
A bad adviser — or a bad piece of advice from an otherwise good one — can quietly do real, lasting damage to someone's financial wellbeing. This tool exists to make those red flags visible, in plain language, so you can have a direct, informed conversation with your adviser before a small issue compounds into a big one.
What this tool will never do
It will never recommend a product, fund, or provider.
It will never tell you to buy, sell, or switch anything.
It will never replace your adviser or a proper financial needs analysis.
It flags where your existing plan may fall short of SA rules, benchmarks and good practice — so you know what to ask about.
For investors — and the businesses that advise them
Built first for the everyday investor, with a bespoke option for advice and compliance teams.
For individuals & families
Most people don't have the time, training, or the vocabulary to tell whether their financial plan is actually any good — and get talked past on jargon when they try. Upload what you've already been given and get the same disciplined, rules-based check a qualified planner would run, explained in plain language.
For advice & compliance businesses
Advice practices and compliance teams can run the same rubric internally — a consistent, first-pass check across records of advice that surfaces the same red flags a file review or regulator would, before they do. We offer bespoke internal solutions: a dedicated instance, a rubric tuned to your house view, and integration with your existing compliance workflow.
Use the technology to raise the standard of advice across your firm
Streamline your compliance audits and make sure your advisers give great advice. We build bespoke solutions for advice practices, product houses and compliance teams.
Streamline your compliance audits
Run a consistent first-pass check across every record of advice, so reviewers spend their time on the files that need a human eye.
Help your advisers give great advice
Spot recurring gaps in costs, suitability, needs analysis and disclosure early, and turn them into coaching before they become complaints.
Tuned to your house view
A dedicated instance with a rubric shaped around your products, policies and risk appetite.
Fits your existing workflow
Integration with the compliance and file-review tools your team already uses.
Contact us for a bespoke solution
Tell us a little about your team and we'll get back to you.
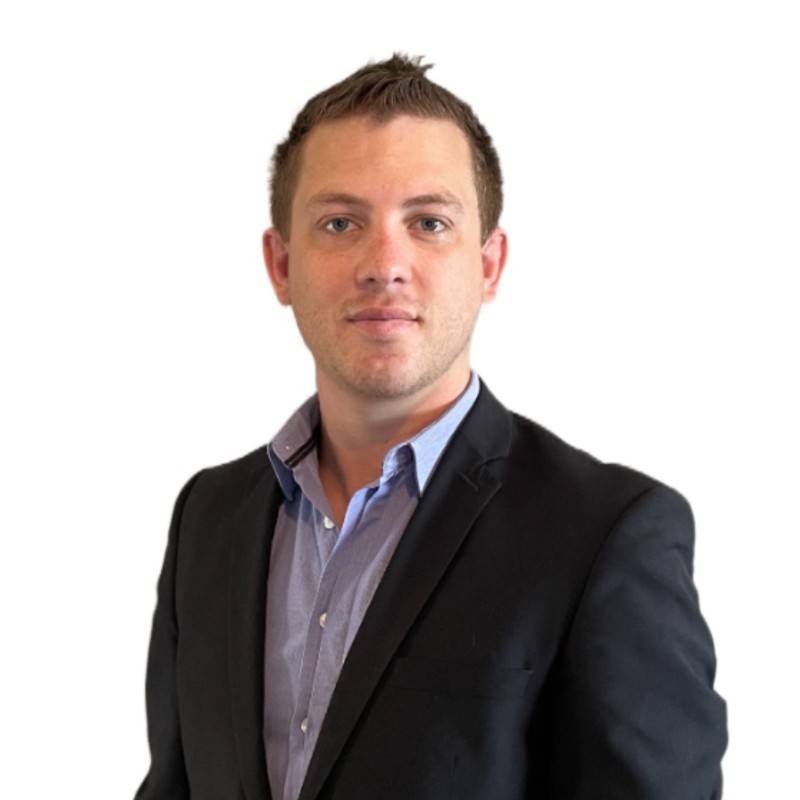
Henry Faul, CFP®
Henry brings over 15 years of practical experience in software engineering, solution architecture, and data-driven systems. He sits at the intersection of technology, business operations, and AI-enabled solutions — uniquely qualified to design a platform that demands all three.
Qualifications15+
years' experience
5
degrees & designations
2
disciplines: tech + finance
Questions people ask first
No. We review advice you've already been given and flag possible problems in plain language. We never recommend a product, fund or provider, and never tell you to buy, sell or switch anything. Take the flags to your adviser, or to another licensed adviser, and talk them through.
Your financial plan, a proposal or quotation, fund fact sheets, or a record of advice. PDF and Word files work, and so do photos or scans of printed pages. You can upload several documents together.
That's fine. We recognise single-need advice and only assess the categories that apply, so you aren't marked down for things the advice was never meant to cover.
Before the review runs, we may ask a few short questions, such as your goal, how long you plan to invest and how much risk you're comfortable with. Each one comes with a plain-language explanation.
We research the adviser, firm, product and provider for FSCA registration, debarment and public reports. Where registration can't be confirmed, the report says so rather than guessing, so always verify with the FSCA directly before acting.
Your reviews are tied to your account and visible only to you. See our disclaimer and data policy for how uploads are handled.
Get a second opinion before a small issue becomes a big one
Upload what you've been given and see where it may fall short — in plain language, with the questions to ask your adviser.